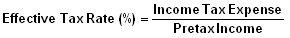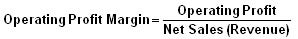The businesses – at least the ones that survive – are ultimately about efficiency: squeezing the most out of limited resources. Comparing profits to revenue is a useful operational metric, but comparing them to the resources a business squeezed to earn them cuts to the very feasibility of a business’ existence.
Return on Assets (ROA) is the simplest of such measures. It’s found in virtually all financial analysis textbooks, but it has a few pitfalls that investors need to know about.
ROA: Good for Banks, Possibly Flawed for Normal Companies
The most common formula for ROA is this:
ROA= Net Income/ Average Total Assets
Higher ROA indicates more asset efficiency. For example, let Mr. Joy and Ms. Keerthi both start road side food truck. Joy spends RS 15000 on a bare second hand truck with cheap accessories, but Keerthi spends 15,0000 on a fairly new truck with hifi accessories. Assuming – mildly unrealistically, but for understanding purpose – those were the only assets each deployed, if over some given time period Joy had earned Rs1500 and Keerthi had earned Rs1,2000, Keerthi would have the more valuable business but Joy wo have the more efficient one since his ROA is 10% (=1500x100/15000) as against 8% for Keerthi!
Joy's ROA: 1500/1,5000 = 10%
Keerthi's ROA: 1,2000/15,0000 = 8%
Despite its popularity in textbooks, this ROA formula is really most suitable for banks.
Why? Banks have different accounting. For example, bank balance sheets better represent the real value of their assets and liabilities because they’re carried at market value (via mark-to-market accounting), or at least an estimate of market value, versus historical cost.
But more relevant here is that whereas for normal companies, debt is investment capital added to a business – capital on which a return is paid to debt investors – for banks, debt is conceptually a fuzzy blend of invested capital and “inventory” from which bank products are created.
Because it’s hard to separate capital from inventory on the balance sheet, it’s likewise hard to separate which interest payments are for a bank’s operations (which would be subtracted out in arriving at operating income) and which are for its financing (which would be subtracted out after operating income) on the income statement. But if we just skip to net income, we find that both interest expense and interest income are already factored in.
As banking metrics go, ROA is an all-in, broad-brushstroke-type of measure. Like all metrics, it gets its relevance from both comparisons to a company’s own historical ROA as well as the ROA of industry peers.
Note that specifically because of banks’ big leverage, there is a huge difference between banks’ ROA and their Return on Equity (ROE), and small differences in ROA can result in much larger differences in ROE – a metric even more important to bank equity investors.
How to Correct ROA for Normal Companies
For normal companies, debt and equity capital is strictly segregated, as are the returns to each: interest expense is the return for debt providers; net income is the return for equity investors. (Even though equity investors don’t generally get paid that net income, they still own it theoretically.)
The common ROA formula jumbles things up by comparing returns to equity investors (net income) with assets funded by both debt and equity investors (total assets). While not an analytical crime, this does muddy the waters for assessing debt vs. equity returns and potency of debt usage, as well as for comparing ROAs among companies with differing debt ratios. Technically, if a company and its comparables all have no debt, this mixup wouldn’t matter, but in the real word, that’s rare.
Two variations on this ROA formula fix this numerator-denominator inconsistency by putting interest expense (net of taxes) back into the numerator:
ROA variation 1: Net Income + (Interest Expense*(1-tax rate)) / Total Assets
ROA variation 2: Operating Income*(1-tax rate) / Total Assets
These variations try to hit substantially the same target, albeit from different starting points. Variation 1 is arguably slightly more robust because net income also includes interest income (generated on cash invested), whereas operating income does not.
The “wrongness” of the simplified formula will vary with the level of debt. But that also means that a simplified ROA that appears to be growing nicely year-over-year may just be growing because a company is taking on more and more debt, and not because business conditions are actually improving.
Return on Tangible Assets (Return on Net Assets)
If you read this far, you’re not in a rush, so let’s cover what’s essentially one variation hiding inside separate names and formulas. The logic here is that companies may have a lot of goodwill (the amount it paid for acquisitions in excess of their fair market value) or other intangible assets that are often closer to accounting fictions than real-life assets at work earning returns. The goodwill account has also been associated with accounting manipulation. For these reasons, some analysts prefer to yank it out in hopes of computing a return on “real” tangible assets at work:
Return on Tangible Assets = (net income + (interest expense*(1-tax rate)) / (total assets - goodwill and other intangibles)
Return on Net Assets gets at the same thing by limiting the denominator to (fixed assets + net working capital); we won’t get into net working capital here, but the idea remains to boot goodwill and related intangible assets like acquired (not developed) patents, mailing lists, brand names, etc. out of the denominator.
ROA: Some People Don’t Like the Denominator
Accounting wonks with an axe to grind will point out that total assets tends to be moderately larger than total capital (defined as equity + debt) because the total assets figure includes not only capital, but also non-interest bearing liabilities like accounts payable, taxes payable, and accrued expenses. These are instances where a company is stalling payment on something; they’re certainly obligations a company must pay, but the accounting logic is that they are not strictly investment debt in that no interest-rate-type return is expected by the receiving party. Therefore, they are not invested capital.
The thrust of the denominator argument is that bang-for-buck profitability measures that straddle the income statement and balance sheet most ideally compare actual returns to expected returns. That means comparing actual ROE to a company’s estimated cost of equity, and actual return on invested capital (ROIC) to a company’s estimated cost of capital. It makes sense. Although total assets may be just a bit larger than total capital, the two numbers are officially different, and at least a small fraction of total assets are “provided” by entities other than investors seeking returns.
Yet even these hardballs would likely agree that ROA is a reasonable metric for banks, and that it’s not erroneous to compare adjusted ROA (adjusted to include interest expense) across ordinary firms for a measure of how efficiently those firms use their total asset base to generate income.
Likewise, virtually all analysts of any ideology would agree that ROA is definitely not the best measure of a business’ bang-for-buck profitability. For better metrics, we need to turn to ROEand ROIC, which are coming up next in next posts.