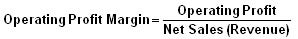Monday, 7 May 2018

Some raw facts about Value Investing

Value investing is at its core the marriage of a contrarian streak and a calculator.

The single greatest edge an investor can have is a long-term orientation.

A margin of safety is necessary because valuation is an imprecise art, the future is unpredictable, and investors are human and do make mistakes. It is adherence to the concept of a margin of safety that best distinguishes value investors from all others, who are not as concerned about loss

Most investors are primarily oriented toward return – how much they can make – and pay little attention to risk – how much they can lose.

Investors should always keep in mind that the most important metric is not the returns achieved but the returns weighed against the risks incurred. Ultimately, nothing should be more important to investors than the ability to sleep soundly at night.

In investing there are times when the best thing to do is nothing at all.

Overvaluation is not always apparent to investors, analysts, or managements. Since security prices reflect investors’ perception of reality and not necessarily reality itself, overvaluation may persist for a long time.

Once you adopt a value-investment strategy, any other investment behaviour starts to seem like gambling.

Value investing requires a great deal of hard work, unusually strict discipline, and a long-term investment horizon. Few are willing and able to devote sufficient time and effort to become value investors, and only a fraction of those have the proper mind-set to succeed.

In reality, no one knows what the market will do; trying to predict it is a waste of time, and investing based upon that prediction is a speculative undertaking.


Saturday, 5 May 2018

Effective tax rate

The effective tax rate is the simple tip of a complicated iceberg.
The simple explanation: Thumb (or scroll) to the income statement and divide “Provision for income taxes” by “Income before income taxes” and you’ve got it. Note that nomenclature may vary, but it’s all the same thing.

 
Relative to much of the world, the Indian/ US tax and accounting rules are lengthy and complex enough to create an industry of lobbyists and loophole specialists. And while we as investors and analysts don’t need to geek out on taxes per se, it’s smart to know the principles at play.
Apart from the formula itself, the main thing to know is that the effective tax rate isn’t a company’s only tax rate. It’s part of a posse of tax rates and tax rate-related concepts that live on – and in some cases, off – a company’s financial statements, feeding into and off of each other.

Profit Margin Analysis

We find accounting profitability exclusively on the income statement, which projects four levels of profit or profit margins: gross profit, operating profit, pre-tax profit and net profit (Profit after tax-PAT).
Conceptually, the income statement assumes the following sequence: A company takes in sales revenue, then pays direct costs of the product of service. What’s left is gross margin. Then it pays indirect costs like company headquarters, advertising, and R&D. What’s left is operating margin. Then it pays interest on debt and adds or subtracts any unusual charges or inflows unrelated to the company’s main business with pre-tax margin left over. Then it pays taxes, leaving net margin, also known as net income or otherwise called profit after tax (PAT) which is the very bottom line.
Three logistical points before getting to the math:

1. Semanticallly, “profit,” “income,” and “margin,” are all used interchangeably, although margin usually refers to a %, whereas profit and income exclusively denote monetary amounts.
2.  When talking about profitability analysis, percentages are more frequently used than raw numbers because they enable comparison among companies and across a company’s own time horizon.
3. Finding margin numbers is easy these days. You can never go wrong pulling the actual numbers from a company’s filings, but many of financial websites have them pre-calculated. Be careful though! Auto-calculating tools have been known to goof on rare occasion.

The Major Margins


  1. Quoting profits in raw INR (or other currency) terms and using percentage terms both come with problems. The raw currency number accurately depicts aggregate profit, but it is a clunky tool for comparison. Percentages accurately show per-unit profitability, but say nothing about units sold. 
  2. The income statement tells us very little about capital structure. A company could issue a slug of debt or sell a bunch of shares to get cash to boost sales and profits, but profits alone don’t reveal whether this was a value-adding move for shareholders.
  3. Income statement numbers are based on accrual accounting, and are thereby more subject to manipulation than cash flows.
  4. The income statement (at least under many countries’ accounting rules) doesn’t fairly capture the economics of all industries. For Real Estate Investment Trusts (REITs), for example, most analysts massage net income into a measure called funds from operations (FFO) that undoes an accrual called depreciation. Plug-and-chug types may miss these nuances if not careful.


EBITDA: Earnings Before Bad Stuff?
Framing the Margins:

The major profit margins all compare some level of residual (leftover) profit to sales. For instance, a 42% gross margin means that for every 100rs in revenue, the company pays 58rs in costs directly connected to producing the product or service, leaving 42rs as gross profit.
Margin of Error: Caveats About Using Income Statement Profit Margins
The key limitation in divining profitability solely from the income statement is caveat (2) above: The income statement tells us only part of the profit picture – the inflows and immediate expenses used to generate those inflows – but not about the capital resources, like asset or equity base, required. For that, we’ll have to look at the balance sheet (and another lesson).

One profitability number you won’t see on the income statement, but will see in a lot of other places (especially the haunts of investment bankers and Wall Street analysts) is earnings before interest, taxes, depreciation, and amortization, or EBITDA.
EBITDA, which would fit in between gross profit and operating profit were it to be on the income statement, is simply operating profit (or earnings before interest and taxes; i.e., EBIT) with the previously subtracted accrual charges of depreciation (the “D”) and amortization (the “A”) added back in.

What’s the point?
EBITDA came into vogue among 1980s investment bankers looking for a quick and dirty cash flow proxy (the Statement of Cash Flows wasn’t the norm until 1988). EBITDA caught a second wave in the tech-crazed 1990s, when earlier and earlier-stage companies saw IPO and acquisition interest.
Acquisition types like to express prices in terms of multiples of profit or cash flow: 20 times earnings, 12 times EBIT, etc.. But many hot companies of this generation didn’t have positive net income (so P/E multiples were out), and often had losses at the pre-tax and operating levels, too. Undeterred, bankers and sell-side Wall Street analysts went up and then off the income statement to produce a number more likely to be positive and easily comparable for early stage companies: EBITDA.
The value of EBITDA depends on its use. The metric leaves out a number of relevant expenses (“earnings before bad stuff” is one nickname), and the metric arguably sees too much use as a proxy for cash flow. Such cases suggest either poor understanding or even a shade of manipulativeness on behalf of the user.
Apparently, WD-40 didn’t get the memo about EBITDA’s warts: Page 21 of its 2016 proxy proclaims that EBITDA is both the #1 and #2 metric (per-segment, and consolidated, respectively) in determining management’s bonus. Fortunately, management appears to be well-behaved and effective, but an EBITDA target is considered risky because it leaves the door open for management to borrow vast sums of money to juice sales and EBITDA: The metric is blind to interest expense, debt outstanding, and capital expenditures.

Gross Profit Margin: Start with sales and take out costs directly related to creating or providing the product or service like raw materials, labor, and so on – typically bundled as "cost of goods sold,” “cost of products sold,” or “cost of sales” on the income statement – and you get gross margin. Done on a per-product basis, gross margin is most useful for a company analyzing its product suite (though this data isn’t shared with the public), but aggregate gross margin does show a company’s rawest profitability picture.
Companies have some discretion about whether to include certain expenses in cost of goods sold (COGS) or “selling, general and administrative” (SG&A) expenses, one expense line down the income statement. 
Note that our gross profit and gross margin may not be comparable to those of other consumer product companies, since some of these companies include all costs related to distribution of their products in cost of products sold, whereas we exclude the portion associated with amounts paid to third parties for shipment to our customers from our distribution centers and contract manufacturers and include these costs in selling, general and administrative expenses. 

Operating Profit Margin: By subtracting selling, general and administrative, or operating expenses, from a company's gross profit number, we get operating income, also known as earnings before interest and taxes, or EBIT.
Operating profit is a big deal, sometimes more so than net income. All the costs of actually providing the product or service have been taken out, resulting in an income figure that’s available to pay both types of capital providers to the business (debt and equity holders), as well as the tax department. Operating profit is profit from a company’s main, ongoing operations; oddball accounting adjustments like income from discontinued operations and extraordinary items are accounted for below this line (they do get bundled into pre-tax income, discussed below). Accordingly, operating income feels purer and less prone to weird accounting-related fluctuations to analysts than net income. Finally, because operating income is conceptually “owned” by both debt and equity holders (whereas net income is just for equity holders, interest expense having been paid), it’s frequently used by bankers and analysts to value an entire company for potential buyouts.

Pretax Profit Margin: Take operating income and subtract interest expense while adding any interest income, adjust for non-recurring items like gains or losses from discontinued operations, and you’ve got pre-tax profit, or earnings before taxes, or EBT. 

Net Profit Margin: If someone asks you, “What’s your company’s profit margin?” they’re most likely asking about net profit margin, or a company’s bottom line after all other expenses, including taxes and one-off oddities, have been taken out of revenue. If you’re a stockholder net income is what you “own,” at least conceptually. If it feels like everybody and his brother gets paid before you do, it’s true. Unlike everybody else, who gets paid a set amount, you as a shareholder get whatever is left, be it much or little. Technically, you seldom actually get it: the company may choose to reinvest that profit, stockpile it, squander it, buy back shares, or pay shareholders a dividend (in which case you actually would get it, or at least some of it). But wherever it goes, net profit, as long as it’s not squandered, adds value to shareholders like us, which is why we bought the stock in the first place.

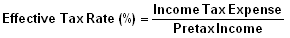
Cash Ratio

The cash ratio is another measurement of a company’s liquidity and their ability to meet their short-term obligations. The formula for the cash ratio, like the current and the quick ratio, uses current liabilities as the denominator in the formula: (Cash + marketable securities) divided by current liabilities

The elimination of accounts receivables used in both the current and quick ratios, and the elimination of inventories that are part of the numerator of the current ratio, leaves us with a ratio that shows the level of the firm’s cash and near-cash investments relative to their current liabilities.

Worst-case scenario:
The cash ratio is almost like an indicator of a firm’s value under the worst-case scenario where the company is about to go out of business. This ratio tells creditors and analysts the value of current assets that could quickly be turned into cash, and what percentage of the company’s current liabilities these cash and near-cash assets could cover.

The cash ratio is seldom used in financial reporting or by analysts in the fundamental analysis of a company. It is not realistic for a company to maintain excessive levels of cash and near-cash assets to cover current liabilities. It is often seen as poor asset utilization for a company to hold large amounts of cash on its balance sheet, as this money could be returned to shareholders or used elsewhere to generate higher returns. While providing an interesting liquidity perspective, the usefulness of this ratio is limited.

Quick Ratio

The quick ratio, also known as the acid-test ratio, is a liquidity ratio that further refines the current ratio by measuring the level of the most liquid current assets available to cover current liabilities. The quick ratio is more conservative than the current ratio because it excludes inventory and other current assets, which generally are more difficult to turn into cash. A higher quick ratio means a more liquid current position.

The formula for calculating a company’s quick ratio is: (Cash equivalents + marketable securities + accounts receivables) divided by Current liabilities

By focusing on the current assets that are generally the easiest to convert to cash, the quick ratio is conceivably a better barometer of the coverage provided by these assets for the company’s current liabilities should company experience financial difficulties.

Inventory is generally considered to be less liquid than these other current assets.

A rule of thumb is that a quick ratio greater than 1.0 means that a company is sufficiently able to meet its short-term obligations.

What the ratio tells us:

A low and/or decreasing quick ratio might be delivering several messages about a company. It could be telling us that the company’s balance sheet is over-leveraged. Or it could be saying the company’s sales are decreasing, the company is having a hard time collecting its account receivables or perhaps the company is paying its bills too quickly.

A company with a high and/or increasing quick ratio is likely experiencing revenue growth, collecting its accounts receivable and turning them into cash quickly and likely turning over its inventories quickly. Factors unique to different companies and industries will also impact a company’s quick ratio, such as the timing of capital expenditures and other asset purchases, allowances for bad debt and other financial policies. When looking to use the quick ratio to compare companies, the most valid comparison is generally between companies in the same industry.

QR is not as such a perfect indicator!

The elimination of inventories makes the quick ratio a somewhat better barometer of a company’s ability to meet its short-term obligations than the current ratio. But like the current ratio, the acid-test ratio is still not a perfect gauge. It is not realistic to assume that a company will liquidate all current assets that comprise the quick ratio to cover short-term debts since the company still needs a level of working capital to remain a going concern.

Current Ratio

The current ratio measures the ability of a company to cover its short-term liabilities with its current assets.

The formula is- Current assets divided by current liabilities

For example, a company with 10,00000 INR in current assets and 50000 INR current liabilities would have a current ratio of 2.0 times.

A current ratio of 1.0 or greater is an indication that the company is well-positioned to cover its current or short-term liabilities.

A current ratio of less than 1.0 could be a sign of trouble if the company runs into financial difficulty.

Cautions in using this ratio:

When looking at the current ratio, investors should be aware that this is not the whole story on company liquidity. It’s also important  to understand the types of current assets the company has and how quickly these can be converted into cash to meet current liabilities.

For example, how quickly can the company collect all of its outstanding accounts receivables? An analyst would want to look at the company’s days sales outstanding which is a measure of how long it takes the company to receive payment after a sale is made.

For companies with inventory, how quickly can this inventory be liquidated should the need arise and what percentage of the inventory’s value would the company be likely to receive? Looking at the company as a going concern, an analyst would want to calculate the company’s inventory turnover ratio, a measurement of how long it takes a company to turnover or sell its inventory.

The current ratio inherently assumes that the company would or could liquidate all of most of its current assets and convert them to cash to cover these liabilities. In reality this is unlikely if the company is to remain as a going concern. A certain level of working capital will still be needed.

Companies with a seemingly high current ratio may not be safer than a company with a relatively low current ratio. Beyond just looking at the current ratio, an analyst would need to look at the composition and quality of the company’s current assets. The current ratio is just one of many financial indicators that potential investors and creditors will need to analyze.

Thirty Main Financial Ratios

When it comes to investing, analysing financial statement information (also known as quantitative analysis), is one of, if not the most important element in the fundamental analysis process. At the same time, the massive amount of numbers in a company's financial statements can be confusing to many investors. However, through financial ratio analysis, you will be able to work with these numbers in an organized fashion which I will guide you through.
The objective of this post is to provide you with a guide to sources of financial statement data, to highlight and define the most relevant ratios, to show you how to compute them and to explain their meaning as investment evaluators.
Among the dozens of financial ratios available, 30 measurements that are the most relevant to the investing process are chosen & organized into six main categories as per the following list:

1) Liquidity Measurement Ratios:

1. Current Ratio
2. Quick Ratio
3. Cash Ratio
4. Cash Conversion Cycle

2) Profitability Indicator Ratios:

1. Profit Margin Analysis
2. Effective Tax Rate
3. Return On Assets
4. Return On Equity
5. Return On Capital Employed

3) Debt Ratios:

1. Debt Ratio
2. Debt-Equity Ratio
3. Capitalization Ratio
4. Interest Coverage Ratio
5. Cash Flow To Debt Ratio

4) Operating Performance Ratios:

1. Fixed-Asset Turnover
2. Sales/Revenue Per Employee
3. Operating Cycle

5) Cash Flow Indicator Ratios:

1. Operating Cash Flow/Sales Ratio
2. Free Cash Flow/Operating Cash Ratio
3. Cash Flow Coverage Ratio
4. Dividend Payout Ratio

6) Investment Valuation Ratios:

1. Per Share Data
2. Price/Book Value Ratio
3. Cash Flow Coverage Ratio
4. Price/Earnings Ratio
5. Price/Earnings To Growth Ratio
6. Price/Sales Ratio
7. Dividend Yield
8. Enterprise Value Multiple

Each of which is decoded & explained in a simple way in the subsequent posts.